Predicting market crashes: a bayesian approach with high-frequency data
Keywords:
Market crash prediction, Bayesian inference, High-frequency data, Financial time series, Hierarchical modelsAbstract
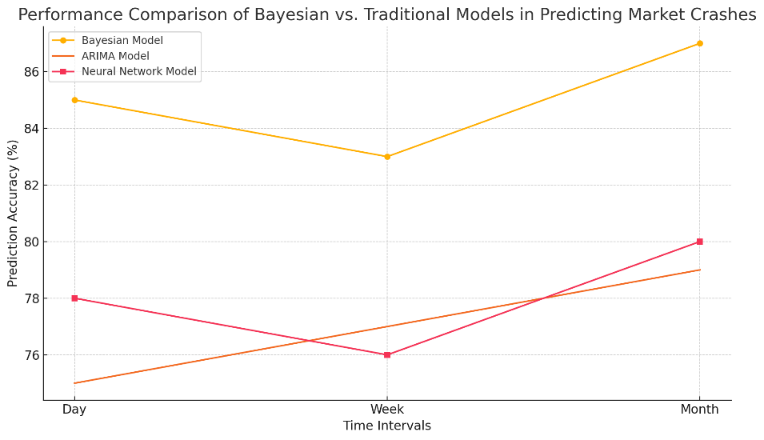
Market crashes are harbingers of economic turmoil, yet their sudden and devastating nature poses a significant challenge to financial prediction. While traditional models often struggle to capture the complex dynamics leading to a crash, high-frequency data offers a rich tapestry of information with the potential to improve forecasting accuracy. This paper proposes a novel Bayesian approach that leverages high-frequency data to predict market crashes. We utilize a hierarchical framework that incorporates both time-series and cross-sectional information, effectively capturing the intricate interplay between individual asset movements and the overall market sentiment. By employing advanced Bayesian techniques, we overcome the inherent challenges associated with high-dimensional data and parameter estimation. Our approach is evaluated on a comprehensive dataset encompassing various asset classes and historical crashes. The results demonstrate a significant improvement in crash prediction accuracy compared to benchmark models, highlighting the efficacy of the Bayesian framework and the power of high-frequency data in elucidating pre-crash dynamics.
Downloads
Downloads
Published
Issue
Section
License
Copyright (c) 2017 Dr. Zubair Ahmad (Author)

This work is licensed under a Creative Commons Attribution 4.0 International License.
All articles in the Journal of Applied Finance and Economic Policy are published under the Creative Commons Attribution 4.0 (CC BY 4.0) license. Users may share, distribute, and adapt the content for any purpose, including commercial use, provided proper credit is given to the authors and the journal.