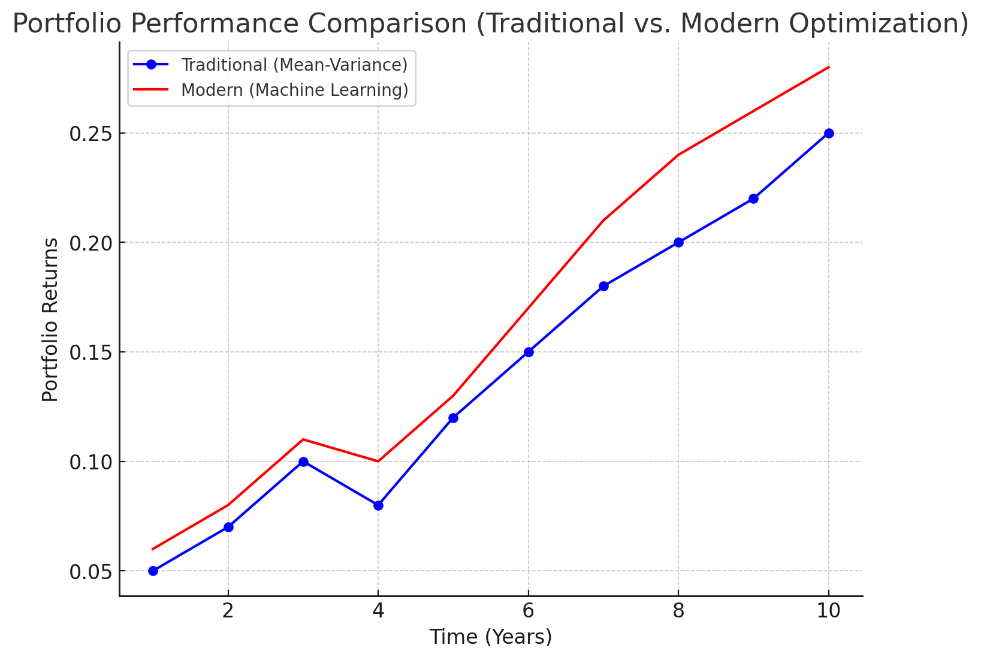
Does portfolio optimization still matter? A comparison of traditional and modern methods
Keywords:
Decentralized Finance (DeFi), Decentralized Exchanges (DEXs), Automated Market Makers (AMMs), Liquidity, Price Discovery, Cryptocurrencies, Bid-Ask Spread, VolatilityAbstract
Liquidity, the ease with which an asset can be bought or sold without significantly impacting its price, plays a crucial role in efficient markets. In the burgeoning world of cryptocurrencies, where decentralized exchanges (DEXs) are challenging the dominance of centralized platforms (CEXs), understanding the price of liquidity takes on particular importance. This article investigates the relationship between liquidity and price on DEXs, utilizing a comprehensive dataset of trade orders and prices across leading platforms. Our analysis reveals that liquidity in DEXs comes at a premium, manifested as wider bid-ask spreads and higher price volatility. This premium is attributed to several factors, including the fragmented nature of DEXs, the reliance on automated market makers (AMMs), and the inherent uncertainty associated with on-chain transactions. We further explore the impact of market depth and trading volume on the liquidity premium, highlighting the non-linear relationship between these factors and price discovery. Our findings offer valuable insights for market participants navigating the evolving landscape of cryptocurrency trading, emphasizing the trade-off between decentralization and the frictionless execution associated with deeper liquidity pools.
Downloads
Downloads
Published
Issue
Section
License
Copyright (c) 2017 Dr. Asma Khan (Author)

This work is licensed under a Creative Commons Attribution 4.0 International License.
All articles in the Journal of Applied Finance and Economic Policy are published under the Creative Commons Attribution 4.0 (CC BY 4.0) license. Users may share, distribute, and adapt the content for any purpose, including commercial use, provided proper credit is given to the authors and the journal.